
Flood Insurance in New York, New Jersey & Florida
Your homeowners policy doesn't cover flood. We compare NFIP and private flood coverage side by side so you get the right protection at the right price.
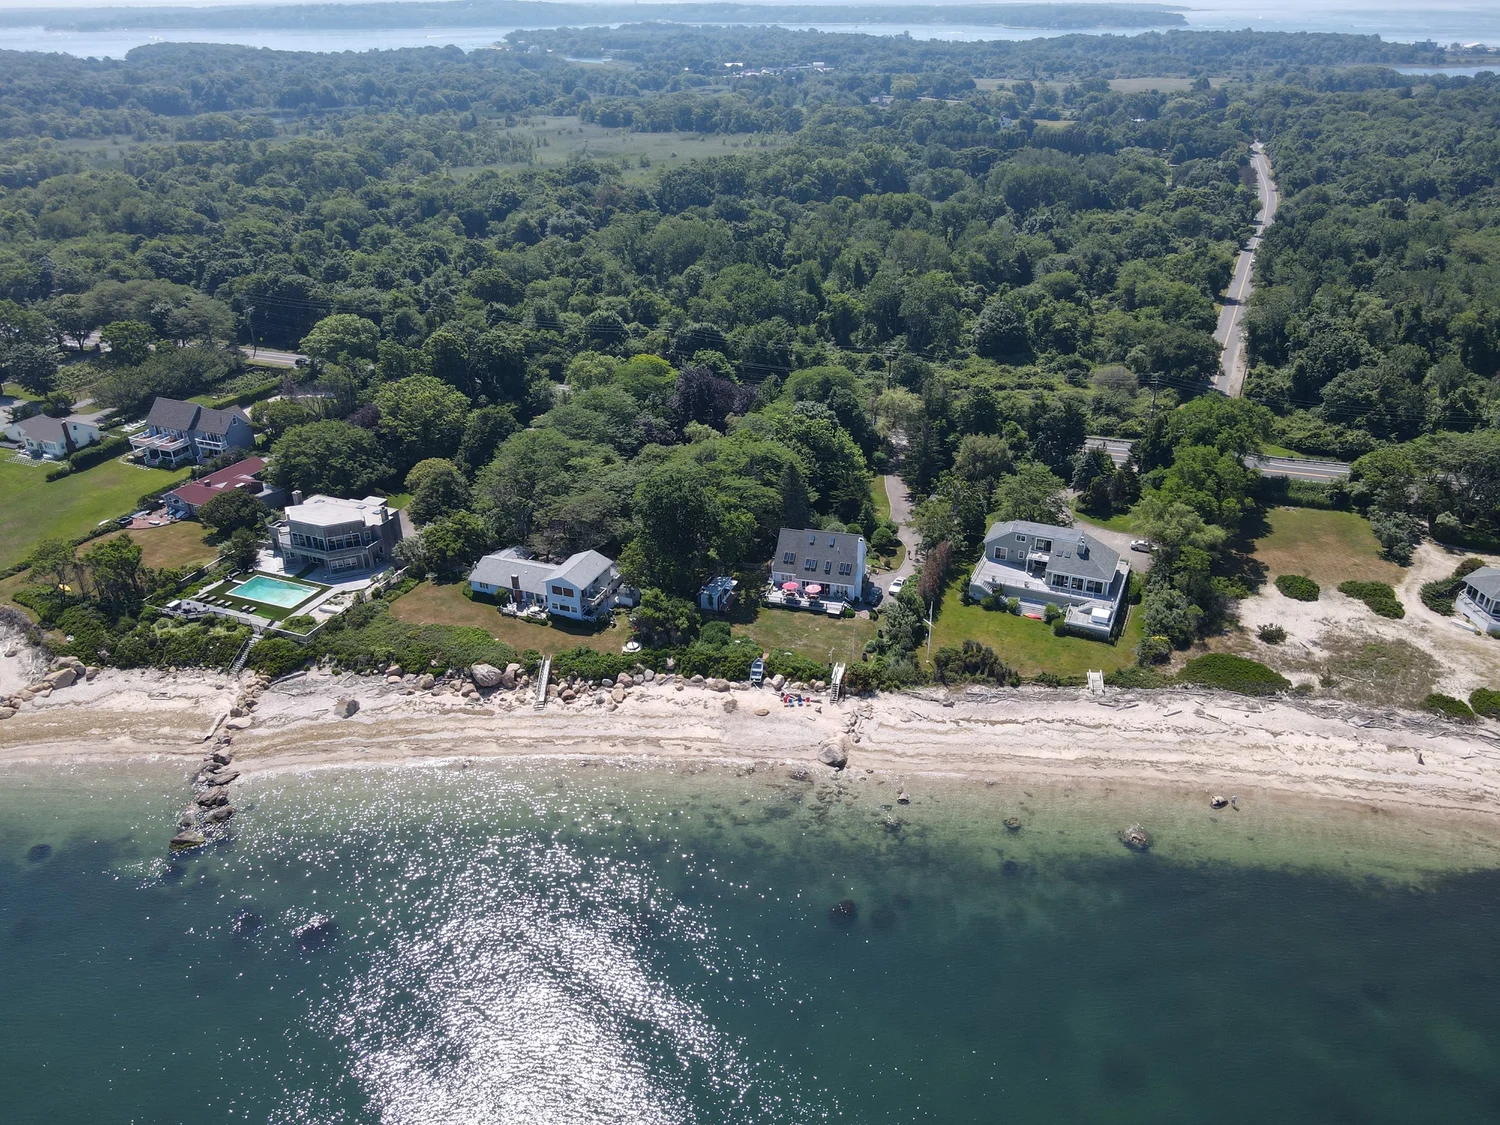
You don't have to be on the water to flood
Whether your home sits on Long Island Sound, the Jersey Shore, a Florida canal or miles inland, heavy rain and storm surge can put water where it doesn't belong.
Flood carriers we’re appointed with
One quote request and we compare NFIP and private flood options from every carrier below.
Why flood coverage matters
Sellis Brokerage helps homeowners across New York, New Jersey and Florida compare government (NFIP) and private flood coverage side by side, so you get the right protection at the right price.
Two ways to insure against flood
- Available in participating communities, including most of New York, New Jersey and Florida
- Up to $250,000 for the building and $100,000 for contents on a home
- Usually a 30-day waiting period, with exceptions such as coverage bought at a home closing
- Policies can often be transferred to a buyer when you sell
- Higher limits for high-value and waterfront homes worth more than NFIP caps
- Options NFIP doesn't offer, like additional living expenses and replacement-cost contents
- Often a shorter waiting period, and competitive pricing for elevated or well-protected homes
- Availability and terms vary by property and carrier
Not sure which is right? We quote both and walk you through the differences, so you can choose based on real numbers. Get both quotes →
Understanding your flood zone
What we need
Send what you have and we'll fill in the rest together.
- Property address and year built
- Foundation type (slab, crawlspace, basement, or elevated on piers or pilings)
- Elevation certificate, if you have one
- Your current flood declarations page, if you're insured today
- The building and contents limits you'd like
Flood insurance questions
Does my homeowners policy cover flooding?
No. Standard homeowners, condo and renters policies exclude flood. You need a separate flood policy.
How soon does flood coverage start?
NFIP policies generally have a 30-day waiting period, with some exceptions, such as a purchase tied to a mortgage closing. Many private flood policies have shorter waits. Don't wait for a storm in the forecast to buy.
Do I need flood insurance if I'm not in a flood zone?
It isn't required, but it's strongly recommended. Homes outside high-risk zones flood too, and coverage there usually costs much less.
Does flood insurance cover my basement?
NFIP basement coverage is limited. It includes items like your furnace, water heater, electrical panel and cleanup, but not finished walls, flooring or most belongings stored there. Some private policies offer broader basement coverage.
Will flood insurance pay for a hotel if I can't live at home?
NFIP policies don't include additional living expenses. Many private flood policies do, which is one reason to compare both.
How can I lower my flood insurance premium?
Under FEMA's current rating approach, NFIP premiums reflect each home's individual risk, including distance to water, elevation and rebuilding cost. An elevation certificate, flood vents or raised utilities can help lower your price, and private flood may be more competitive for elevated or well-protected homes.
Protect your home before the next storm
Tell us about your property and we'll shop NFIP and private flood options for you, at no cost to you.